Why have your own expert?
After a fire, flood or storm, your insurer appoints its own expert (the expert d’assurance). They inspect the damage, check what your policy covers and put a figure on the loss. That figure becomes the insurer’s settlement offer.
The insurer’s expert is instructed and paid by the insurer. They are not there to advise you, and nobody checks their figures on your behalf. Damage that is hidden or appears later can be missed, repairs can be priced at the lowest rate, deductions for age and wear (vétusté) can be applied heavily, and some damage can be put down to existing defects that the policy doesn’t cover.
You have the right to be assisted by your own expert (expert d’assuré) at any stage of the claim. We inspect the property, establish the cause, document every item of damage and prepare a full costed claim. We then meet the insurer’s expert at a joint inspection (expertise contradictoire) and negotiate the figures, item by item, in French, with the evidence in front of both sides.
If the two experts cannot agree, many policies provide for a third expert to settle the difference. And where your policy pays new-for-old (valeur à neuf), we make sure the amount held back for age and wear is claimed once the repairs are done.
We regularly work alongside insurers, loss adjusters, other parties’ experts and court-appointed experts, and we know how French claims and disputes run in practice.
How a claim works with your own expert
Living abroad? Many of our clients own a home in France but live in the UK or elsewhere. We can be your eyes on the ground: visiting the property, dealing with the insurer’s expert in French and keeping you informed in English.
Damage we deal with
From our case files
Real damage we have assessed
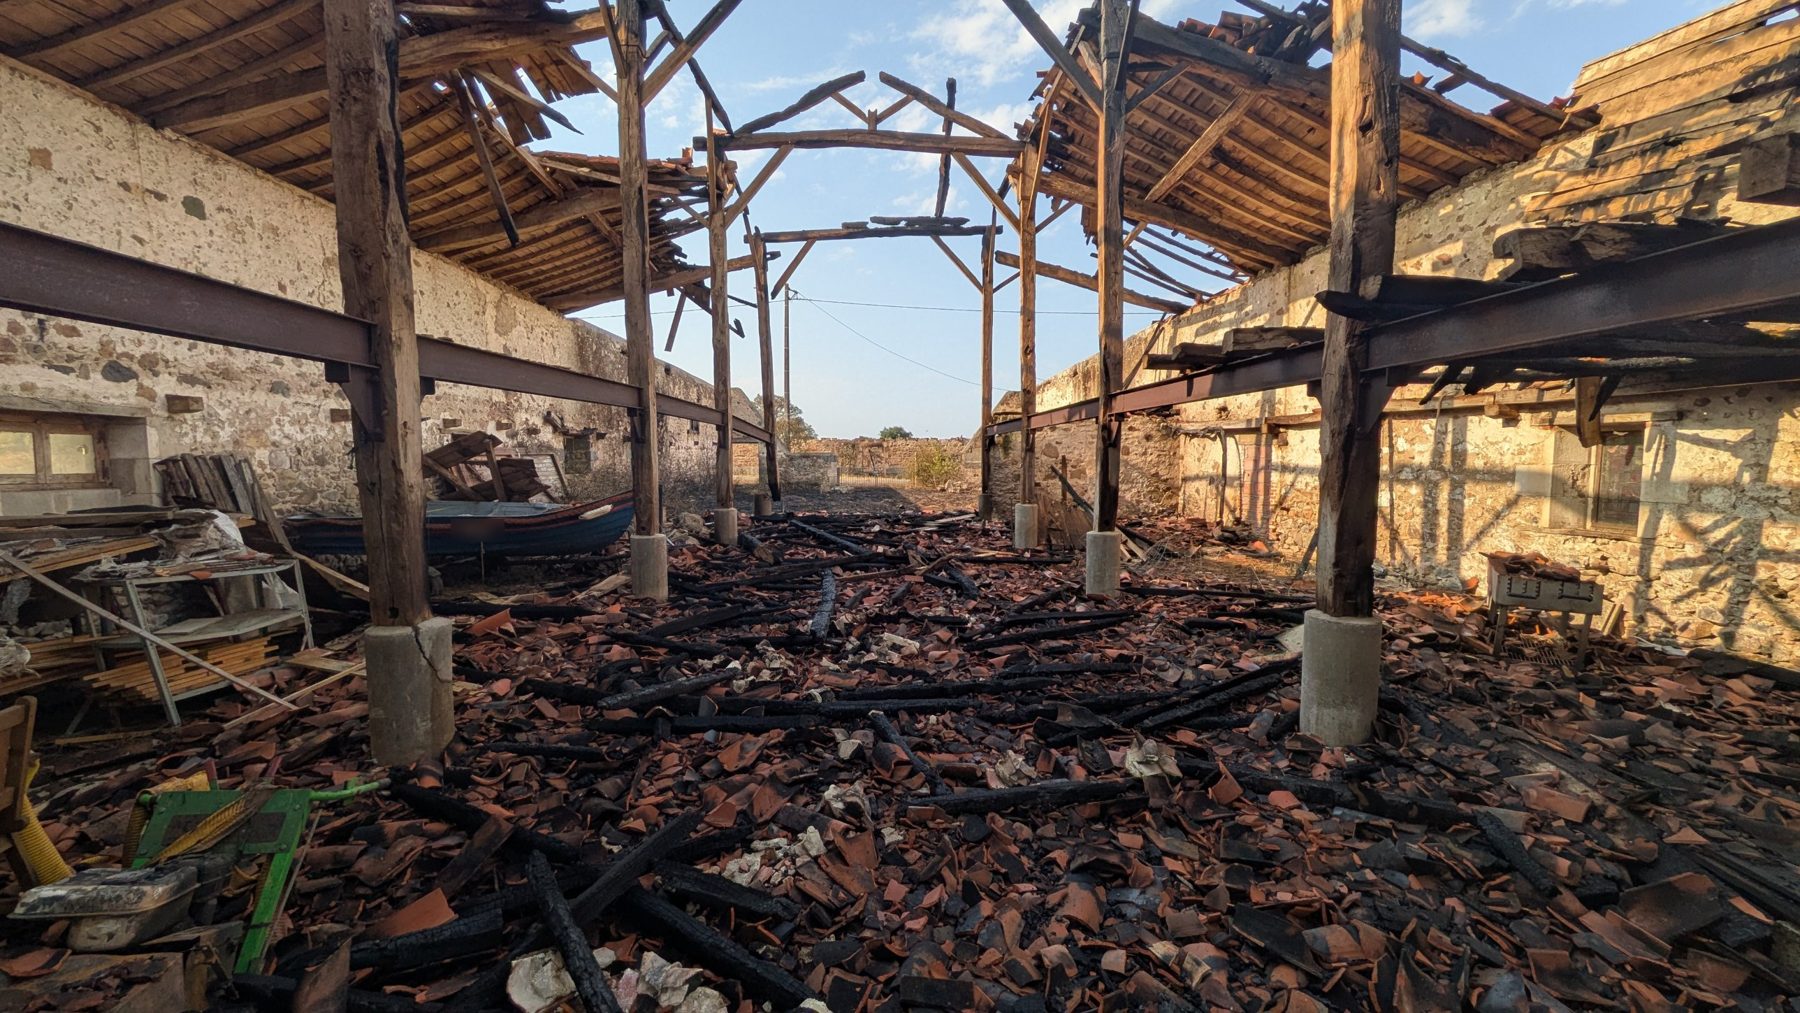
Photographs from fire and flood cases we have worked on in France. Every claim starts the same way: a careful record of the damage, before anything is cleared away.
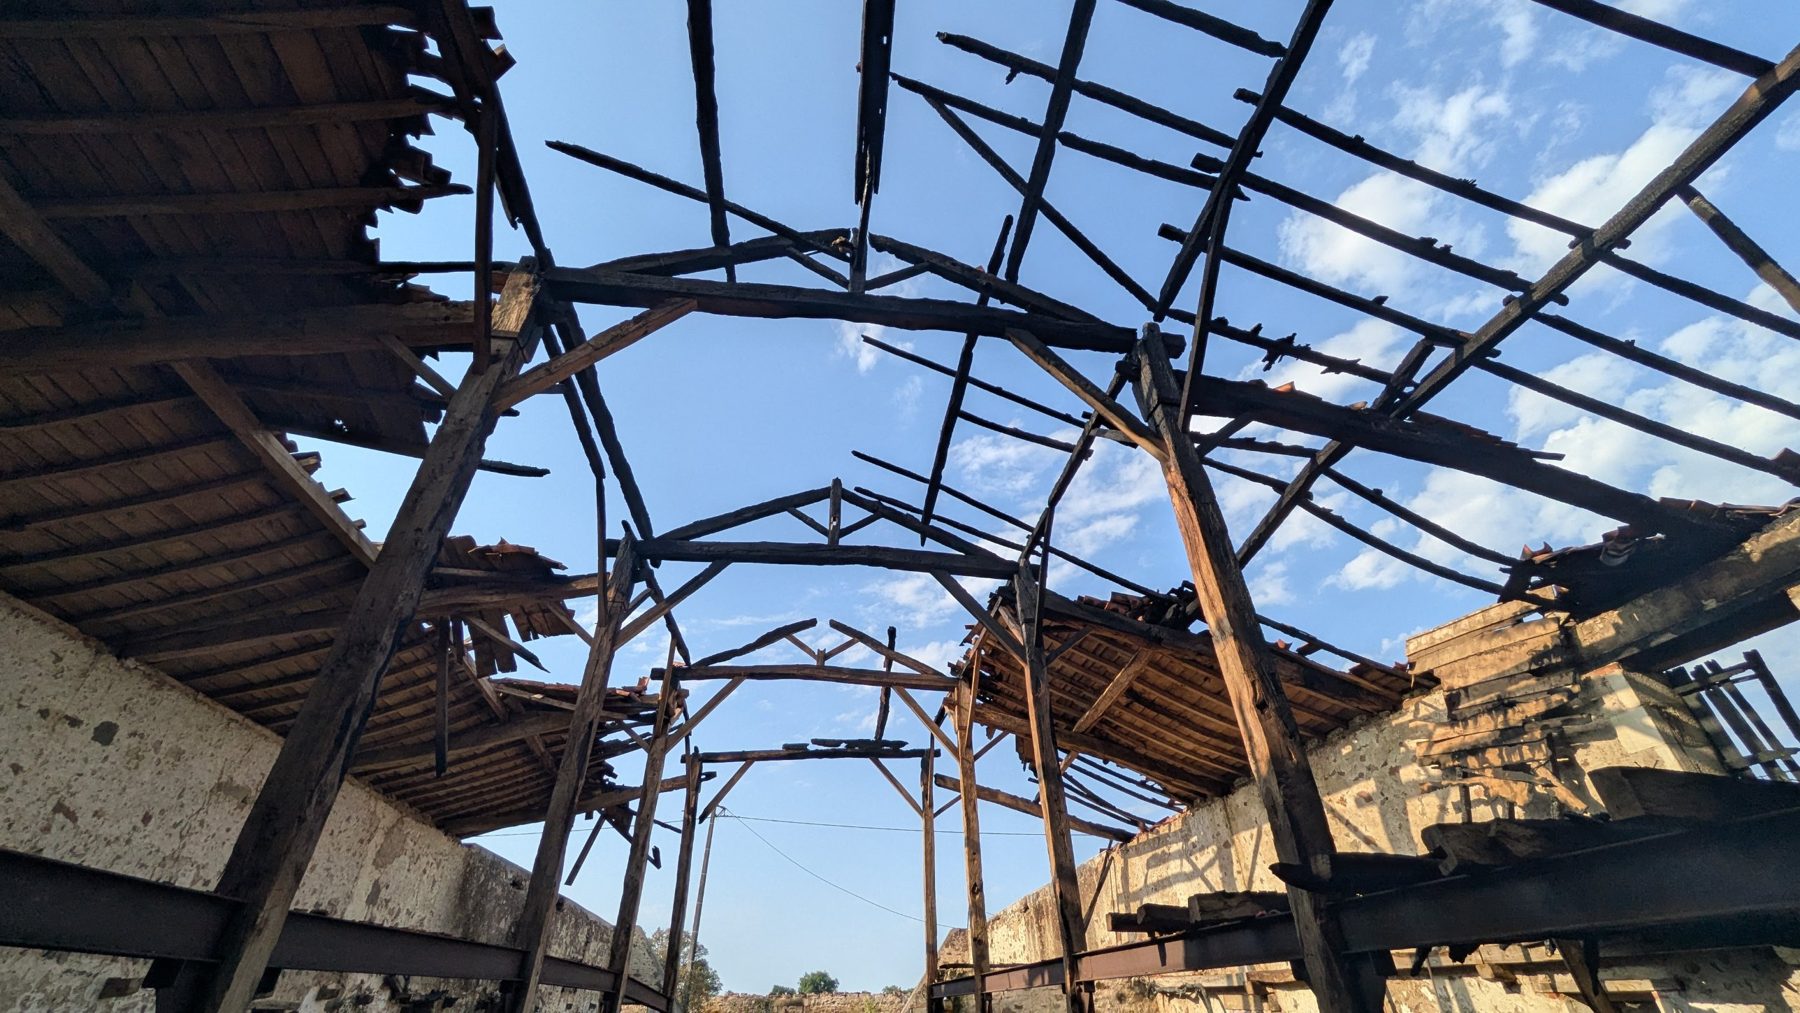
Fire: roof covering and battens lost, main trusses still standing.
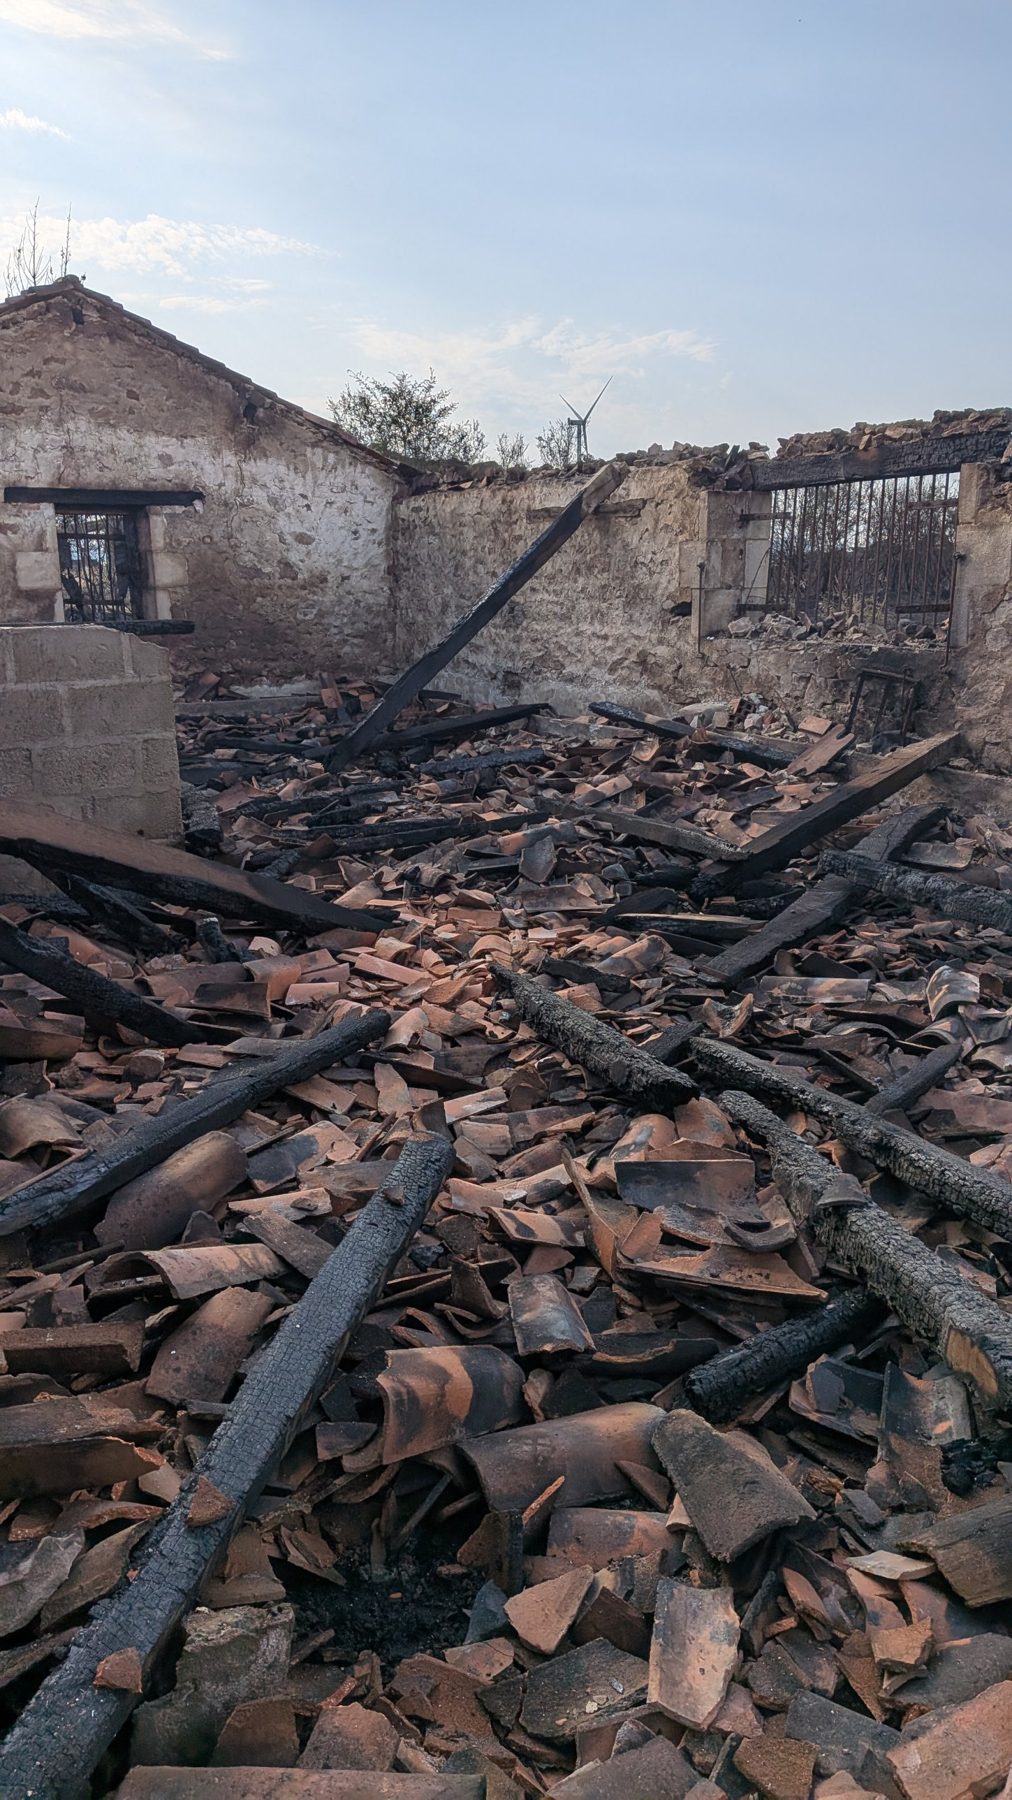
Fire: collapsed roof, burnt beams and broken tiles.
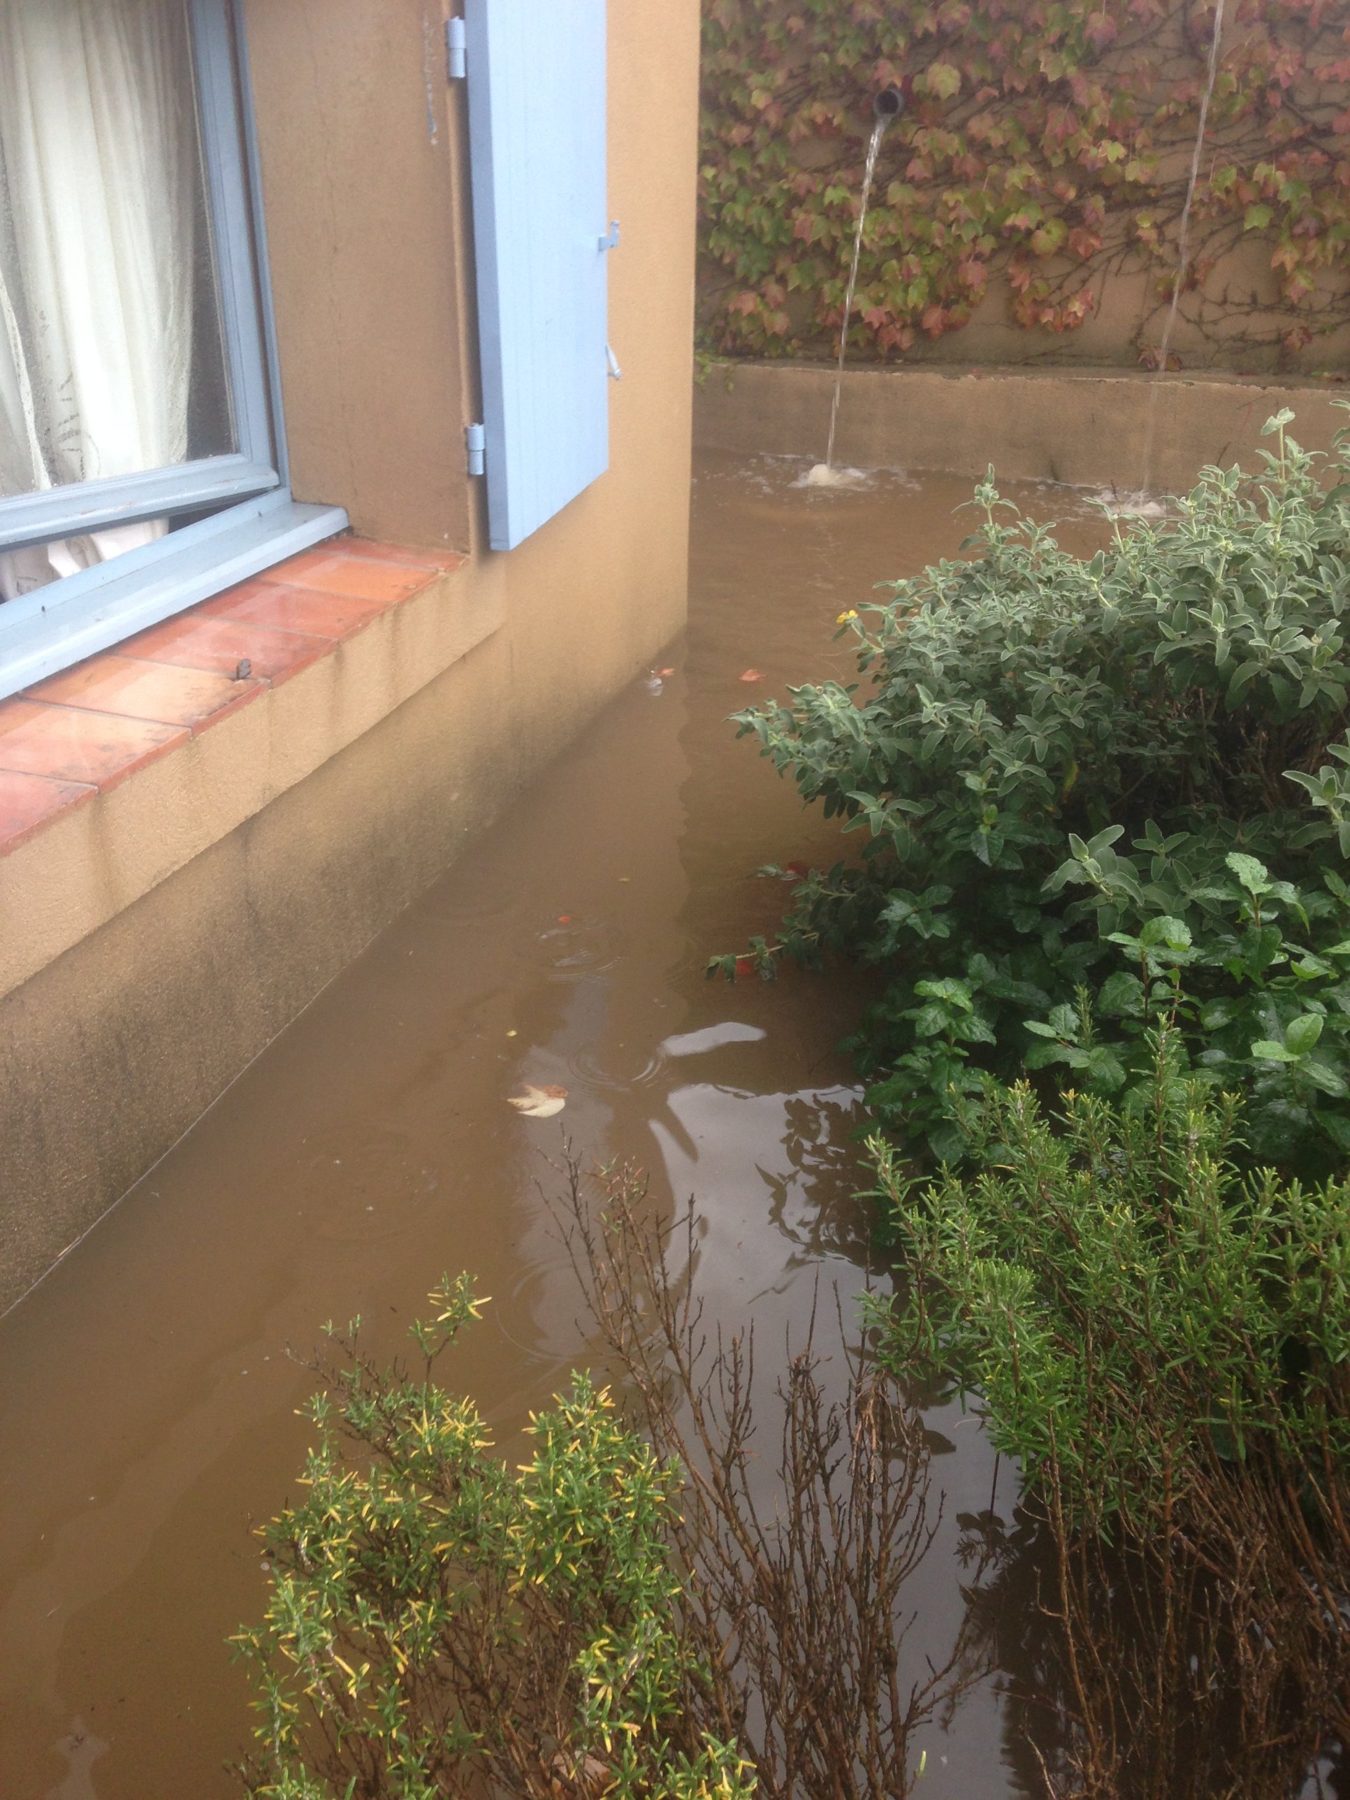
Flood: water at sill height against the walls.
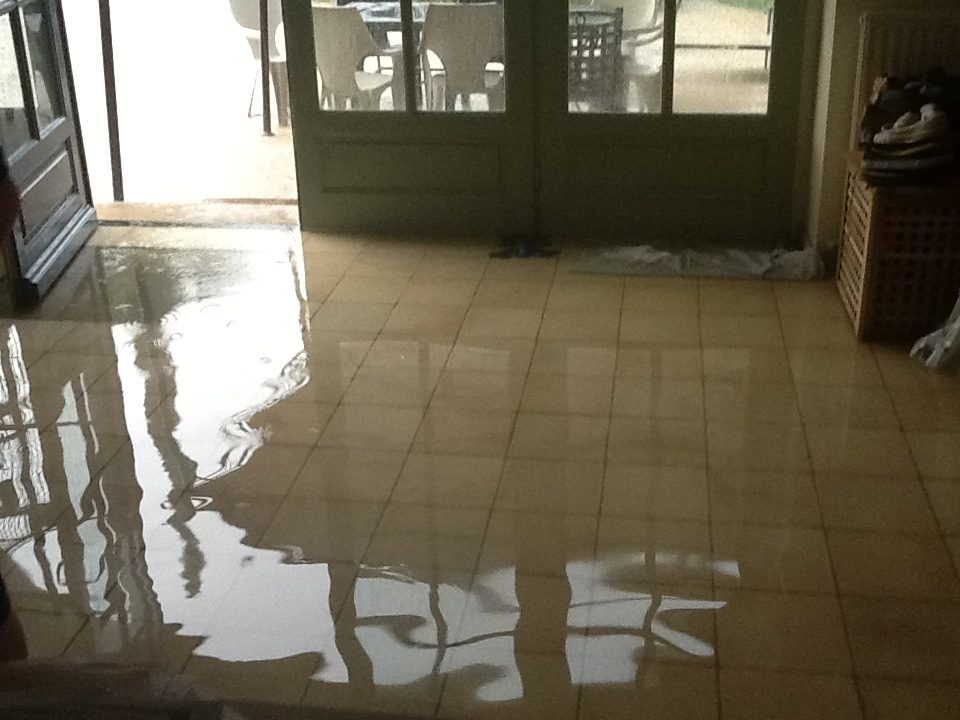
Flood: water across a tiled ground floor.
From claim to recovery
A claim is only the first step. We stay with you until the property is safe and the work is under way.
Act quickly
Insurance claims have deadlines. Declare the loss to your insurer as soon as you can, keep photographs and damaged items until the expert has seen them, and don’t start permanent repairs before the damage is assessed. For drought or flood damage covered by a natural-disaster decree, the deadline to declare runs from the date the decree is published: check with your insurer straight away.